

Insurance for Sole Traders

Built for freelancers, contractors, and the self-employed
Instant quotes, immediate cover
Fast, hassle-free claims support
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:


On this page:
What is sole trader insurance?
Sole trader insurance are the cover options designed for businesses that are owned and operated by one person. It covers the cost of legal fees, compensation, and other unexpected expenses, such as:
- Customer property damage claims
- Third-party injury claims
- Client losses related to your professional advice, errors, or negligence
- Cyberattacks and data breaches
- Damage to owned business buildings, contents and stock
- Loss, damage, or theft of business equipment, and tools
- A serious injury that leaves you unable to work
Public Liability insurance is the most common type of insurance taken by sole traders. It covers you if a third-party claims that your negligent business activities caused them injury or property damage (including defence costs).
It is important for sole traders to select the right occupation when they are getting insurance. This helps ensure that your business and work activities are covered correctly.
Australia is home to over 820,000 sole traders1. BizCover offers customisable insurance options to fit their needs—from tradespeople and consultants to bookkeepers, beauticians, creative freelancers, and more.
1 ABS statistics, 26 Aug 2025
Why do sole traders need insurance?
While working for yourself can be rewarding, it also comes with risk. Unlike a company, sole traders are personally responsible for their business debts, taxes, and liabilities. There is no legal separation between the business and its owner.
Without adequate insurance, your personal finances and assets could be at risk to cover legal fees and compensation costs. Claims can come from various everyday risks, such as:
| A mistake in your professional advice causes a client to lose money |
| Another contractor trips over a tool you’ve left out and sprains their ankle in the fall |
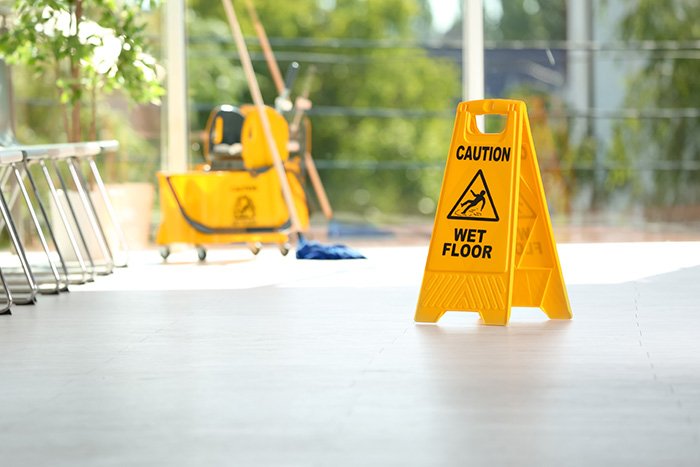
| A client slips in water and is injured in your office |
| You accidentally break a customer’s window while working |
| Your tools, laptop, or other business equipment are stolen from your business premises |
| A cyberattack exposes your customer payment details |
| You’re injured on holiday and are unable to work for weeks |

Get a professional or trades license
Secure a business loan
Work as a contractor or sub-contractor
Lease a workshop, office, or shop
Who is sole trader business insurance for?
Business insurance is considered important by many businesses, including sole traders. [DT5.1]BizCover offers customisable insurance options to thousands of self-employed occupations and sole traders, including:

Don’t see your industry or occupation? Compare quotes online or on the phone 1300 249 268 and get covered today.
Do I need sole trader business insurance?
Business insurance is not legally mandated for all sole traders. However, there are many instances where individual sole traders may be required to have insurance, including:
- It is legally required to receive a professional or trade licence. Professional Indemnity or Public Liability insurance are often required for sole traders working in certain occupations and industries. These requirements vary by industry, state, or territory.
- It is required to join a professional association. Many industry associations require their members to have Professional Indemnity or Public Liability (or sometimes both) to join or receive accreditation.
- It is mandatory because you have employees. Workers’ compensation insurance is required for Australian businesses with employees, even if the business is registered as a sole trader. (BizCover does not currently provide workers’ compensation insurance.)
- It is required by contract to work with certain clients or customers. Professional Indemnity or Public Liability insurance are common requirements written into business contracts and to act as a contractor or subcontractor of another business.
- It is required to work in public spaces. Many councils require sole traders working on council land to have Public Liability insurance (ex: a physical trainer running sessions in a park).
- It is mandatory to lease commercial space for your business. Commercial landlords commonly require Public Liability insurance (and sometimes Glass cover) to lease office, retail, workshop, and other commercial spaces.
Even if insurance is not mandatory for your business, you may still want to be covered. Sole traders are personally and financially responsible for their businesses. Legal fees, compensation payouts, repairs, and other unexpected bills can potentially cost thousands of dollars. Business insurance protects your finances against these and other types of risks.
Types of sole trader insurance
Every business has unique risks and insurance needs. Our sole trader insurance can be customised to fit your business, so you only pay for what you need.

Basic sole trader insurance:


Additional sole trader insurance:




Customised, on-the-go cover your small business
Start a quote to see how much you can save and buy online in minutes.
How much does sole trader business insurance cost?
Sole trader insurance costs can vary based on factors such as your business types and location. Compare quotes from selected leading Australian insurance partners to find out how much you’ll pay.
Facts influencing cost

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
Flexible cover that grows with your business
Choose cover levels to fit your business: Public Liability up to $20 million, Professional Indemnity up to $10 million, Cyber Liability up to $2 million, and Personal Accident & Illness weekly benefit up to $4,000.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
Flexible cover that grows with your business
Choose cover levels to fit your business: Public Liability up to $20 million, Professional Indemnity up to $10 million, Cyber Liability up to $X million, and Personal Accident & Illness weekly benefit up to $4,000.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How to choose the right business insurance as a sole trader
How to choose the right business insurance as a sole trader When comparing sole trader insurance policies, you may want to consider:
- What risks does my business face? Listing potential risks that could impact your business can help you determine which types of cover you may want to purchase.
- Which types of insurance are required (if any)? Consider if you are required to have cover for licencing or accreditation, to meet legal requirements, or meet the terms of a business contract or lease.
- What are the policy limits, exclusions, and deductibles? Some policies may fit your business needs better than others.Read the policy wording to understand its:
- Limits – The most an insurer will pay when you make a claim.
- Exclusions – Activities and risks that are not covered by the policy.
- How much does cover cost? BizCover makes it easy for sole traders to compare multiple quotesand find cover that fits their business and their wallet. You can also choose to pay monthly or yearly, to better match your cash flow.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
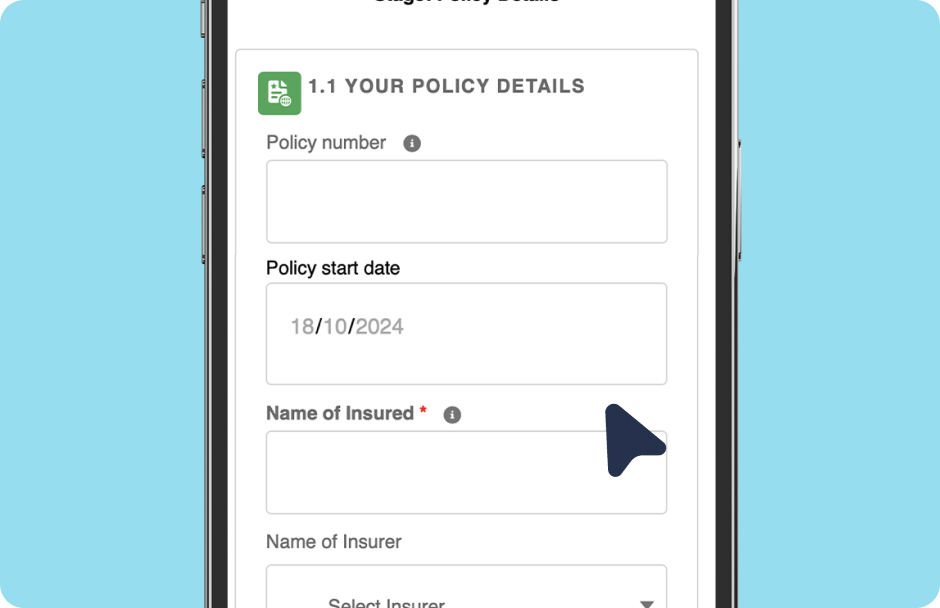
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Other Sole Traders Have Saved By Purchasing a Policy Through BizCover
Kate
Massage Therapist from
NSW
Saved
$150
on
Allied Health Combined Liability insurance
Luke
Handyman from
VIC
Saved
$150
on
Public Liability insurance
Sarah-Jane
Nurse from
TAS
Saved
$400
on
Allied Health Combined Liability insurance
^Savings made from February to August 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
When to get insurance depends on the type of business you run and your business activities. You might consider insurance if:
• You apply for a professional or trades license
• A client, vendor or supplier requires proof of insurance in their contract
• You lease commercial premises for your business
• Clients visit you in your place of work, their premises, or third-party locations
The types of sole trader insurance that you may consider depend on your risk exposures.
Sole traders often consider Public Liability at a minimum. It covers you if a third-party claims that your negligent business activities caused them injury or property damage. This includes defence costs cover.
Professional Indemnity is often required for sole traders to get a professional license. It covers you for losses claimed by a third party and defence costs due to alleged or actual negligence in your professional services or advice.
Personal Accident & Illness insurance provides a weekly income benefit following an accidental injury or illness for a set amount of time, once signed off from work by a medical practitioner. Optional lump sum benefits for disablement and/or death can also be added to some policies.
BizCover also offers insurance solutions to help sole traders protect their business assets, manage cyberattacks, prepare for business interruptions, and more!
Public Liability insurance covers you if a third-party claim that your negligent business activities caused them injury or property damage. This includes defence costs cover.
Some sole traders (such as accountants and real estate agents) are required to have insurance to maintain their professional license, even if they work from a home office or are self-employed. Clients may also require insurance as part of their contracts, regardless of where you do business.
Homeowners policies typically do not cover business activities. Business insurance can help protect you when working from a home office, by covering your business equipment, tools, records, and other assets.
If a member of the public (such as a customer, supplier, or delivery person) claims your negligent business activity injured them or damaged their property, Public Liability insurance can help cover the costs of setting things right.
If you provide clients with professional advice or services, Professional Indemnity insurance can cover legal fees and losses caused by errors or omissions in your work, real or alleged negligence, breaches of contract, and more.
Yes. In Australia, most businesses with employees are legally required to hold workers’ compensation insurance, regardless of their business structure. This applies to full-time and part-time staff, as well as casual workers.
Workers’ compensation insurance covers employees who are injured or fall seriously ill at work. It covers medical costs and lost income while the employee recovers. (Please note: BizCover does not currently offer workers’ compensation insurance.)
However, sole traders themselves are not covered by workers’ compensation policies, as they are not considered employees of a business. Personal Accident & Illness insurance helps sole traders cover this gap. This insurance can cover your income if you’re unable to work due to illness or injury, even if you are injured outside of work. Options are also available to provide lump sum benefits if you are permanently disabled or pass away.
The terms “self-employed” and “sole trader” are both used to describe someone who works for themselves. Sole trader is a business structure that is commonly chosen by self-employed individuals, because it is simple and affordable to set up. However, self-employed individuals can register their business under a different business structure, such as a company.
BizCover makes the claims process as painless as possible for sole traders. Simply complete our online claims form at any time, 24/7 to get started. We’ll manage the claim with your insurer. You can track the progress of your claim online, so you’re always in the loop.
Getting a certificate of currency is easy with BizCover. A certificate of currency will be emailed to you after purchase, and additional copies can be downloaded from the customer portal at any time.
Business insurance checklist for sole traders
- List your potential risks and learn what types of insurance can help you manage them
- Select the correct occupation to ensure your business activities are properly covered
- Compare multiple quotes to find polices that fit your business needs and budget
- Carefully read your policy wordings to understand what you are (and aren’t) covered for
- Review your insurance as your business grows and changes to ensure your cover still fits your needs
Hear from our customers
Looking for trusted small business insurance? This BizCover review shows how quick and easy it is to get covered online.
Very satisfactory experience in attending PI coverage. I’ve recommended BizCover to clients

Anthony
Super easy, the types of insurance cover available were clearly explained. I liked having the option to pay annually.
Frances
Great customer service
Vicki
I was pretty clueless about what I needed, and was helped by two staff – one in Australia and one in New Zealand – to sort out the right cover for my sole trader business.
Trusted Customer


