

Insurance for Builders

Cover built for registered building practitioners
Policies meet state and territory insurance requirements
Public Liability up to $20 million, Professional Indemnity up to $10 million
Cover built for registered building practitioners
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:


On this page:
What does builders’ insurance cover?
Builders’ insurance covers everyday risks faced by registered building practitioners, designers, and other building trades. These risks include:
- Negligence and breach of duty claims
- Mistakes in your work
- Third-party injuries and property damage
- Damaged, lost, or stolen tools
- Injuries that leave you unable to work
Builders work in a highly regulated industry, with strict and evolving regulations. Business insurance helps cover legal and compensation costs for common claims.
BizCover offers fast, tailored cover options to protect your business, finances, equipment, and yourself.
Professional Indemnity for registered building practitioners: Key cover benefits
BizCover offers a Professional Indemnity policy tailored to the needs of building practitioners, featuring:
- Civil liability cover
- Claims investigation and disciplinary costs
- Fidelity cover (optional)
- Retroactive and run-off cover
- Automatic reinstatement
Why do builders need insurance?
Insurance helps builders meet state and territory licensing requirements and meet the terms of work contracts. It also helps cover the cost of claims, lawsuits, and some unplanned expenses.
| Industry-specific Risks | General risks |
|---|---|
| Completion delays lead to a financial loss for the client | Accidentally damaging a client’s property while working |
| Failing to get necessary permits and approvals | Damaged tools, site equipment, or building materials must be replaced to continue work |
| You fail to exercise reasonable care and skill when providing building services | An injury leaves you unable to work for weeks |
Insurance requirements for builders
Builders must meet insurance requirements to become licensed and/or work in most states and territories in Australia.
- New South Wales – Registered building practitioners must hold “appropriate level” of Professional Indemnity insurance from 30 June 2027.
- Northern Territory – Building practitioners must hold a minimum of $1 million in Professional Indemnity insurance.
- Queensland – Must have a minimum of $500,000 to $5 million in Professional Indemnity insurance depending on class of licence held.
- Tasmania – Builders must have a minimum of $5 million in Public Liability insurance.
- Victoria – Specific building practitioner categories must have minimum levels of Professional Indemnity insurance.
- West Australia – Building engineering and building surveying contractors must have “appropriate” levels of Professional Indemnity insurance.
Who needs builders’ insurance?
Business insurance is essential for many types of builders, including residential builders, construction project management, property developers, and many more, like:

Builders
Registered Building Practitioners
Home Renovations or Alterations
Residential Building Construction
Construction Project Management
Commercial Building Construction
Property Developers
House Construction (New Dwellings)
Duplex House Construction
Industrial Building Construction
Apartment Construction
Home Renovations or Alterations
Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
What types of insurance do builders need?
Builders and building practitioners consider different types of insurance to cover their unique industry risks. Customise an insurance package that meets your needs and buy in minutes.

Basic builder insurance:


Additional builder insurance:



How much does builders’ insurance cost?
Business insurance for builders costs an average of $143 per month*.
Factors influencing cost

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual factors will apply.
Get flexible cover to match your business needs
Select cover amounts to suit your business, from sole traders to high-capacity builders: Public Liability up to $20 million, Professional Indemnity up to $10 million, and Personal Accident & Illness weekly benefits up to $4,000.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual factors will apply.
Get flexible cover to match your business needs
Select cover amounts to suit your business, from sole traders to high-capacity builders: Public Liability up to $20 million, Professional Indemnity up to $10 million, and Personal Accident & Illness weekly benefits up to $4,000.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
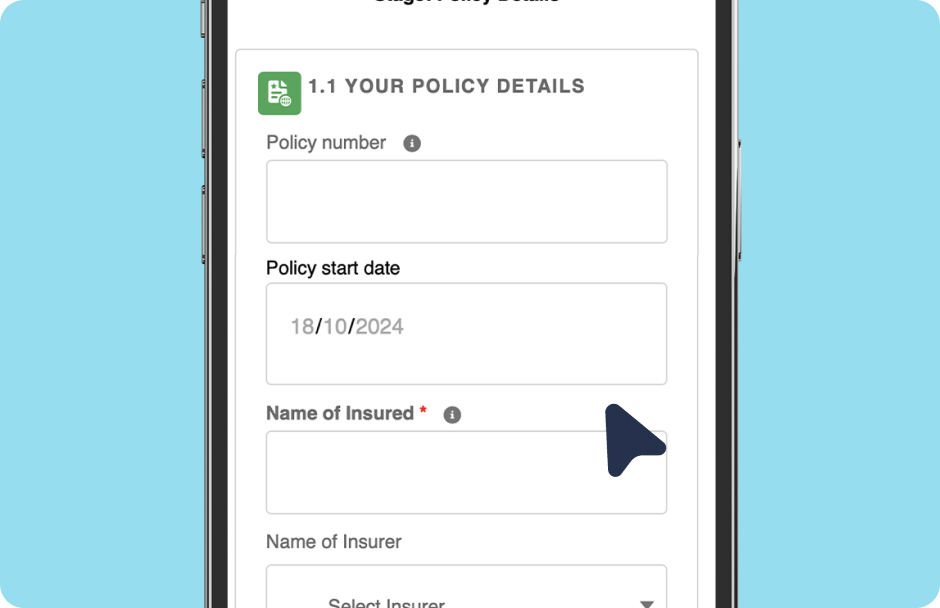
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Others Have Saved By Purchasing a Policy Through BizCover
Colette
Disability Care Worker from
NSW
Saved
$1,200
on
Public Liability and Professional Indemnity insurance
Andrea
Beautician from
VIC
Saved
$1,500
on
Business insurance Pack and,
Public Liability and Professional Indemnity insurance
Deborah
Cleaner from
VIC
Saved
$3,600
on
Public Liability insurance
Lance
Electrician from
ACT
Saved
$800
on
Public Liability insurance
Stephen
IT Professional from
VIC
Saved
$1,500
on
Information Technology Liability insurance
Linda
Restaurant owner from
NSW
Saved
$1,000
on
Business Insurance Pack and
Public Liability insurance
^ Savings made from January 2024 to April 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
Yes, Professional Indemnity insurance is currently required for specific builder occupations in Northern Territory, Queensland, Victoria, and Western Australia. From 30 June 2027, registered building practitioners in NSW will be required to have Professional Indemnity insurance to work in the state, under the Design and Building Practitioner Act 2020.
Public Liability insurance is commonly required to enter jobsites or to work as a contractor or subcontractor for another business. A Public Liability policy may also be required to lease commercial office, workshop, or warehouse space. Builders in Tasmania must have at least $5 million in Public Liability cover to receive a builder licence.
Professional Indemnity insurance for builders does not cover:
• Any provision of design or engineering services, or responsibility for them
• Costs to rectify, repair, replace, complete, or remediate any building work or element
• Costs to rectify, repair, or remediate defective building work
• Property development
• Breach of warranty arising from property development
• Building certification or verification of design compliance
A job-specific or site-specific policy provides cover for a single project or location for a limited period. (Please note: BizCover does not offer job- and site-specific policies.)
Job- and site-specific policies generally provide limited cover compared to a “blanket” policy. Blanket policies can cover work done on multiple sites or projects. They are often easier to manage, as you only need to worry about the details of just one policy. A blanket policy also helps you avoid gaps in cover for ongoing or smaller projects.
Yes. Many policies—including Public Liability and Professional Indemnity insurance—can cover you when working on multiple sites and projects.
Business insurance policies generally last for 12 months. You will need to either renew your policies or switch insurers every year.
Many builders compare new quotes each year before renewal. This helps them decide if their current policy still fits their business needs and helps them find potential savings for their business.
Yes, there are times when self-employed builders need insurance. Insurance may be required for self-employed builders to meet licencing requirements, get on site, work as a contractor or subcontractor, or lease commercial workshop or office space to run their business.
Builders face many unique on-the-job risks, whether they are a self-employed sole trader or run a building business with dozens of employees. Business insurance protects your business, tools, assets, and reputation no matter your size.
Yes, Professional Indemnity insurance is currently required for specific builder occupations in Northern Territory, Queensland, Victoria, and Western Australia. From 1 July 2026, registered building practitioners in NSW will be required to have Professional Indemnity insurance to work in the state, under the Design and Building Practitioner Act 2020.
Builders may need Public Liability insurance to enter jobsites or to work as a contractor or subcontractor for another business. A Public Liability policy may also be required to lease commercial office, workshop, or warehouse space. Builders in Tasmania must have at least $5 million in Public Liability cover to receive a builder licence.
Hear from our customers
Its so good and super easy

Scott A, Builder
More competitive prices
Barry C, Builder
Great Service. Thank you
Harry N. Builder
Great way to cover.
David G. Builder


Real-life customer reviews verified by Feefo