

Insurance for Restaurants Cafes

Customised cover options, including Public Liability, Contents, Machinery Breakdown, and more
Competitive Prices with our Price Promise
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:


On this page:
What is restaurant insurance?
Restaurant insurance is designed to cover the unique risks faced by the food and beverage industry. It can cover unexpected costs and help your business stay open if things go wrong.
Our restaurant insurance options provide protection for:
- Bodily injuries suffered by customers or visitors
- Business property damage
- Equipment and machinery breakdown (e.g., ovens, refrigerators)
- Content, stock or inventory loss
- Business interruptions
- Legal costs and lawsuits
BizCover offers insurance solutions customised for restaurants, cafes, bakeries, ice cream shops, and more. Get a quote online today.
Why should restaurants consider insurance?
Restaurants are fast-paced environments, with high foot traffic and lots of staff. Whether it is slip-and-fall accidents involving customers, property damage, or a broken oven, business insurance helps protect your business against potentially costly claims.
In some cases, restaurants are required to have certain insurance to satisfy contractual and legal requirements. Commercial landlords often require tenants to have Public Liability and Glass insurance to lease a commercial property.
Having restaurant insurance helps you cover various scenarios, such as kitchen fires, broken down fridges, and food poisoning claims.
Here are common risks for food and eatery businesses.
| Common risk scenarios |
|---|
| A waiter drops hot coffee on a customer causing burns |
| During a busy dinner rush, a deep fryer catches fire, causing damage to the premises. |
| An industrial freezer breaks down, causing the food inside to spoil |
| You accidentally served contaminated food, causing multiple customers to fall ill |
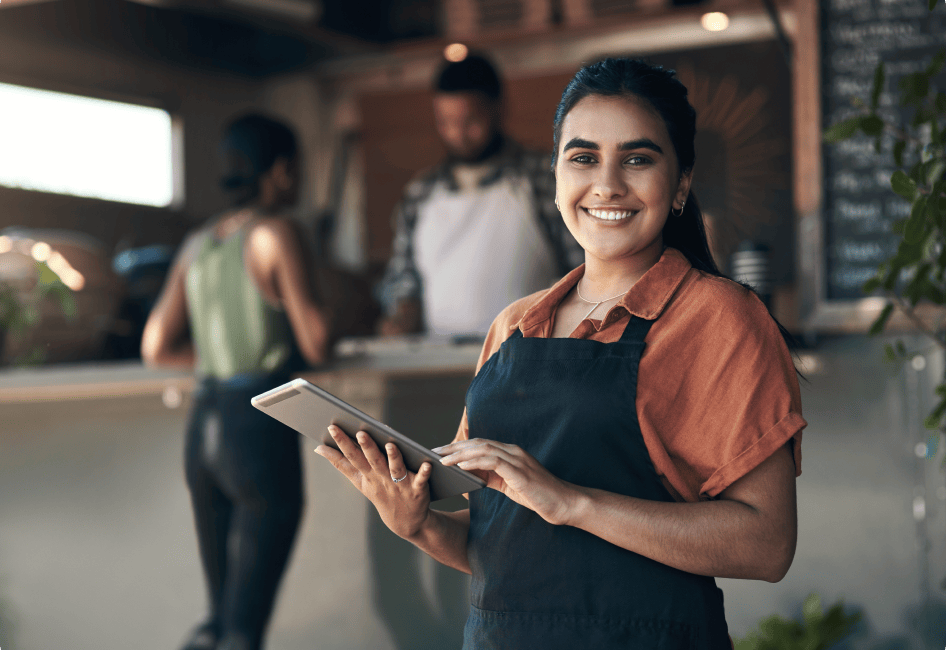
| A customer is injured slipping on a freshly mopped wet floor |
| Storm damage forces you to close your business temporarily |
| Someone breaks in and steals tablets, POS machines, and other essential equipment |
| A hostess files claims against your manager for treating inappropriately |
Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
Who is restaurant and cafe insurance for?
Businesses in the food industry may benefit from restaurant insurance. We offer coverage to a wide range of businesses from family restaurants, buffets, and steakhouses to juice bars and sandwich shops.

Restaurants
Coffee Shops
Catering Services
Takeaway Shops
Fine Dining Restaurants
Fast Food Restaurants
What types of insurance do restaurants need?
We offer a broad range of cover options designed to protect your restaurant premises, equipment, stock, and more. You can combine different types of policies to create cover bundle that suits your business needs.

Basic restaurants insurance



Additional restaurant insurance


How much does restaurants’ insurance cost?
Business insurance for restaurants costs an average of $222 per month*.
Factors influencing cost

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get cover that grows with your business
Choose cover limits that fit your business needs, including Public & Products Liability up to $20 million.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get cover that grows with your business
Choose cover limits that fit your business needs, including Public & Products Liability up to $20 million.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
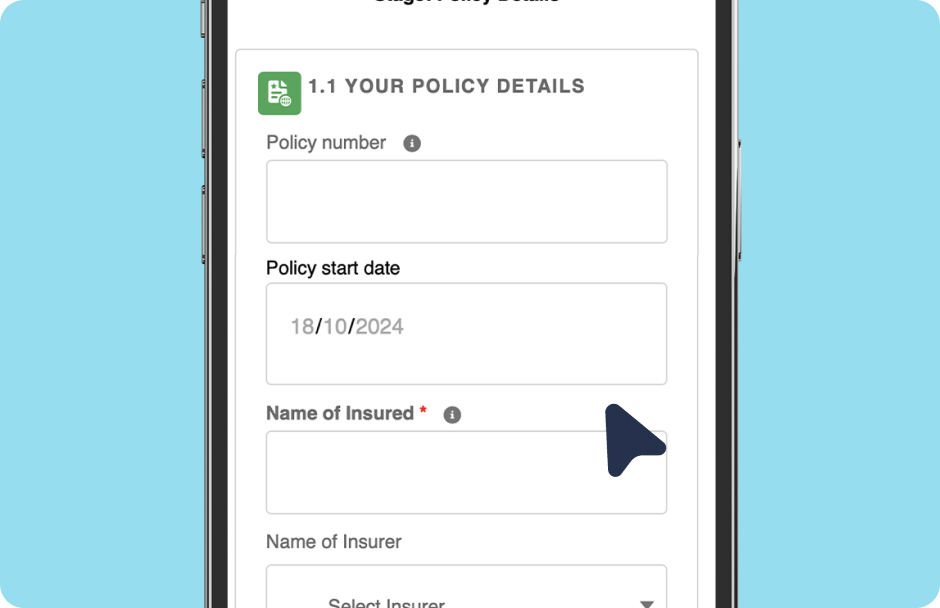
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Other Cafes and Restaurants Have Saved By Purchasing a Policy Through BizCover
John
Cafe Operator from
VIC
Saved
$5,000
on
Business Insurance Pack

Anthony
Coffee Shop Owner from
QLD
Saved
$2,300
on
Public Liability insurance
Leanne
Coffee Shop Owner from
WA
Saved
$200
on
Business Insurance Pack
^Savings made from February to August 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
Certain types of insurance are commonly required to run a restaurant. Commercial landlords often require tenants to have Public Liability insurance to lease commercial space. Commercial lease may also require you to have Glass cover (an option available through a Business Insurance Package).
Commercial restaurant insurance can cover many common risk scenarios, depending on the policy types you choose. Common risks for restaurants include:
• A customer slips on a wet mopped floor and is injured
• A kitchen fire damages essential equipment, forcing you to close until it is replaced or repaired
• A window is broken
• Waitstaff drops food on a customer’s coat and damages it
In most cases, yes. Related businesses (such as a café and takeaway shop) can be covered under the same Public Liability policy if they are run by the same legal entity.
Every restaurant is different, and the amount of Public Liability insurance that each may need will vary. Factors that can impact the amount of Public Liability your restaurant may need include:
• Annual turnover
• Number of staff
• Restaurant location
• Minimums required by a commercial lease agreement
Yes, Public Liability insurance protects against claims related to the service of alcohol (subject to the terms, conditions, and exclusions in the policy wording).
Yes. Public Liability insurance protects against claims related to food or water contamination (subject to the terms, conditions, and exclusions in the policy wording). Most policies designed for restaurants, cafes, and other hospitality businesses cover food poisoning. While your legal liability to injured customers and third parties is generally covered, the cost of recalling contaminated products is not covered.
Yes. Insurance covers restaurants and cafes that use deep fryers and wok cooking (subject to terms, conditions, and exclusions in the relevant policy wording). You will be asked questions about your fryer set up, such as the total litres of oil used and whether your premises has an exhaust extraction system. These answers help match you to the right insurer and can affect pricing.
Yes, restaurant insurance can cover bars and pubs (subject to the terms, conditions, and exclusions in the policy wording). Bars and pubs may need more specialist cover that requires us to work with our insurance partners to create a policy for your business.
With BizCover, getting a certificate of currency for your restaurant is easy. A copy is emailed to you after purchasing a policy, and you can download additional copies any time by logging in to our customer portal.
Hear from our customers
So quick and easy to get a quote and the pricing options are great

Donna
Easy, simple and cost effective
Isaac
Easy and fast
Peter
Easy & simple to use website to get quote. Price is affordable and Qantas point claim.
Pham
Easy and competitive
Michael


Real-life customer reviews verified by Feefo