
Insurance for Carpenters

Cover for contracts with builders or government with minimum cover levels
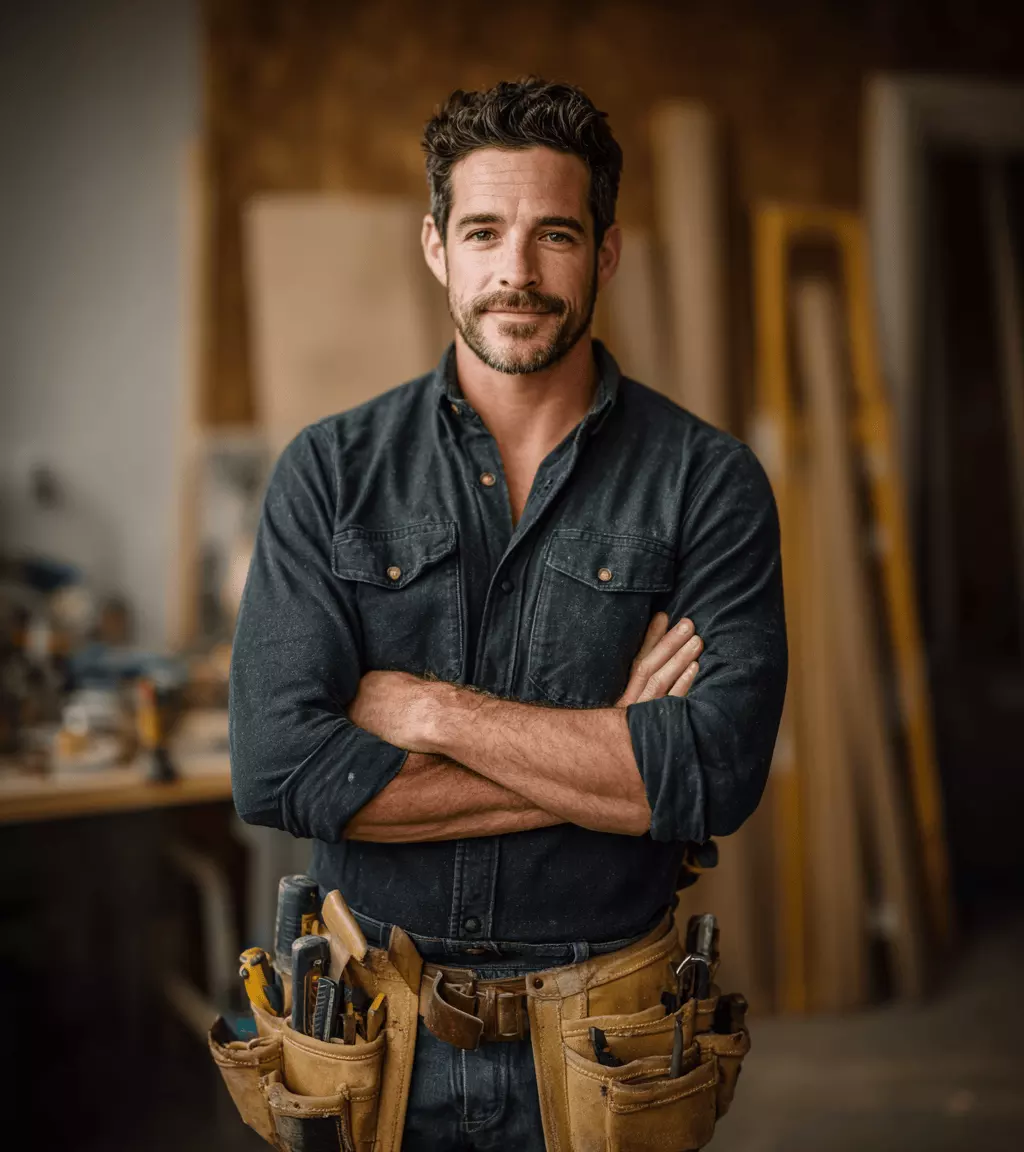
Customised for domestic and commercial projects
100% online, instant proof of cover
Public Liability and Tool cover
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:
On this page:
What does carpenter insurance cover?
Carpenter insurance covers the cost of everyday risks faced by residential and commercial carpenters, joiners, cabinet makers, framers, woodworkers, and other tradespeople. Common risks include:
- Third-party injury and property damage
- Professional mistakes, negligence, and lawsuits
- Vicarious liability
- Damage to someone else’s property in your care, custody, or control
- Lost, damaged, or stolen tools and equipment
- Damaged stock and supplies
- Loss of income due to injury or sickness
Public Liability insurance is the most common type of cover taken by carpenters. It’s typically required to access construction projects, work as a subcontractor, and lease commercial space.
BizCover makes it easy to find affordable, personalised cover that matches your needs, whether you’re a self-employed contractor or running a small carpentry business. We offer policies suitable for builder and government contracts that include vicarious liability.
Why do carpenters need insurance?
Carpenters may need Public Liability insurance to enter worksites, get a building or construction licence, lease a workshop, or work as a subcontractor.
Carpentry is a hands-on trade, with unique risks that could impact your business, finances, and reputation. Having the right insurance for your carpentry business can provide protection against the cost of on-the-job risks, such as accidents, injuries, client claims, and missing tools.
| Industry-specific Risks |
|---|
| An outdoor deck rots prematurely and must be replaced because you recommended unsuitable timber |
| A client alleges that you provided a negligent inspection report |
| Essential tools are damaged and must be replaced before you can continue work |
| A tradie injures themselves when they trip and fall over your toolbox on a worksite |
| You accidentally drill into a pipe while mounting cabinets, causing a water leak and drywall damage |
| A storm damages your workshop and the materials stored inside |
| You are injured on holiday and are unable to work for several weeks |
Who should get carpenter liability insurance
Many types of businesses can benefit from having carpenter insurance, including joinery, woodworking, and construction professionals who work on jobsites, use expensive tools, and act as subcontractors. We cover a range of carpentry occupations, including:

Independent Carpenters & Joiners
Custom Woodworking Businesses
Home Renovation Contractors
Deck Builders
Customised, on-the-go cover for your small business
Start a quote to see how much you can save and buy online in minutes.
Did you know?
Public Liability insurance is generally required for self-employed carpenters, subcontractors, and trades businesses to get a building or construction license, accept jobs, or enter worksites
What types of insurance do carpenters need?
Our carpenters’ insurance is designed to meet the unique needs of carpentry and joinery businesses. Mix and match different policies to build a package that suits your business.

Basic carpenter insurance:


Additional carpenter insurance:


How much does carpenters’ insurance cost?
Business insurance for carpenters costs $99 per month*.
Factors influencing cost

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get flexible cover to match your business needs
Choose limits that suit your business, from sole traders to growing carpentry businesses. Public Liability cover up to $20 million and Professional Indemnity cover up to $10 million. Personal Accident & Illness benefits up to $4,000 a week are also available.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get flexible cover to match your business needs
Choose limits that suit your business, from sole traders to growing carpentry businesses. Public Liability cover up to $20 million and Professional Indemnity cover up to $10 million. Personal Accident & Illness benefits up to $4,000 a week are also available.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
What to look for in carpenter insurance
- Licenced Builders – If you perform carpentry work under your own building licence, your policies may need to be customised to ensure you are property covered for the work you do.
- Height Restrictions – Some policies and/or insurance partners may exclude work above a certain height.
- Subcontractors – If you work as a subcontractor or use them yourself, let us know! It may impact your cover and premium.
Claim example
Here is an example of a real BizCover customer who had to make a claim.
Incident
A carpenter fractured their wrist in a fall and was unable to work. Because they had started a new role since their current policy’s inception, limited earnings information was available to assess their income. An accountant could not complete the carpenter’s tax returns to provide an updated earnings statement until the end of the financial year.
The carpenter was under financial pressure whilst receiving no income, so the insurer agreed to a weekly benefit rate after reviewing their bank statements and a letter from the accountant. The carpenter claimed a Weekly Injury Benefit of $1,250 per week and received a lump sum due to their injuries.
The provision of the claims examples are for illustrative purposes only and should not be seen as an indication as to how any potential claim will be assessed or accepted. Coverage for claims on the policy will be determined by the insurer, not BizCover.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
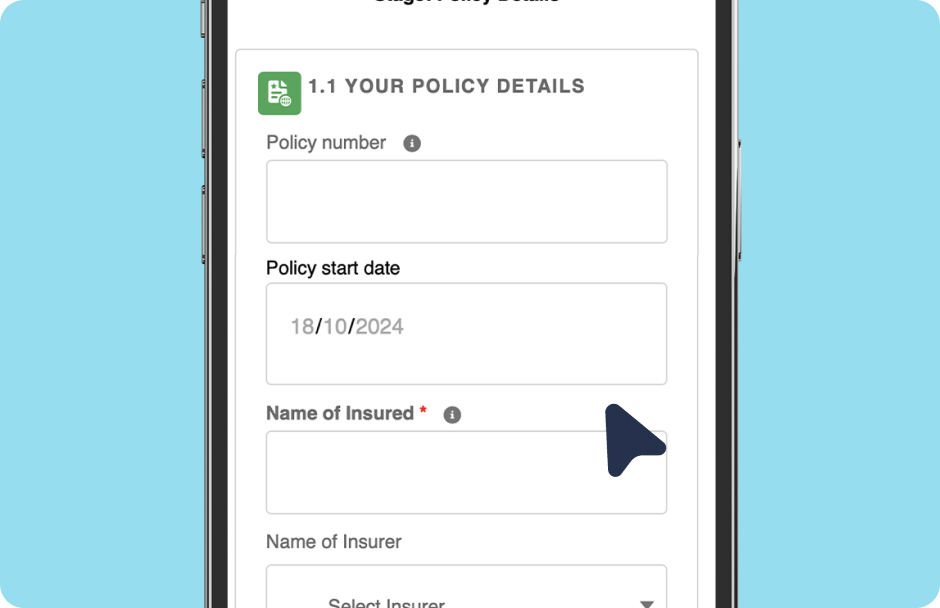
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Other Carpenters Have Saved By Purchasing a Policy Through BizCover
Daniel
Carpenter from
VIC
Saved
$1,000
on
Portable Equipment
Jake
Carpenter from
VIC
Saved
$400
on
Public Liability insurance
Christopher
Carpenter from
NSW
Saved
$200
on
Public Liability insurance
^Savings made from February to August 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
Yes, Public Liability insurance is typically mandatory to enter work sites and lease commercial space for your business (such as an office, workshop, or warehouse).
Yes, principal contractors and builders typically require their subcontractors to have Public Liability insurance to work for them. Your subcontractor agreement will likely specify a minimum cover amount that you must maintain while working.
Carpenters may need Professional Indemnity insurance in some circumstances. A policy may be mandatory in some states and territories if you create architectural plans or structural designs or if you operate as a registered builder. Commercial clients may require a policy to win a project.
Portable Equipment insurance can help repair or replace items like tools, business equipment, electronic items, and stock that are lost or damaged due to theft, fire, and other events. It’s an optional part of a Business Insurance Package that helps protect the tools and equipment needed to run your carpentry business.
Personal Accident & Illness insurance provides a weekly income benefit following an accidental injury or illness for a set amount of time, once signed off from work by a medical practitioner. You can also add optional cover for death and disablement to your policy.
Policy options are available to cover your employees. This must be selected/added before purchasing the policy to include coverage for employees.
Yes. You can usually cover multiple work activities, such as general carpentry and home renovations, in the same policy. Be sure to select all work activities you engage in when applying for insurance that you would like covered.
izCover makes it easy for carpenters to show proof of insurance for licencing, work site access, and client contracts. A certificate of currency is emailed to your instantly after purchase, and additional copies can be downloaded at any time from our customer portal.
Hear from our customers
Great,easy and simple to use

Te Atkins. Carpenter
Thought it was going to be hard but only took me a few minutes on my smoko break
Nathanuel J. Carpenter
Easy to understand and follow. Provided everything I needed
Thomas H. Carpenter
Quick and easy to navigate
Joe H. Carpenter


Real-life customer reviews verified by Feefo