
Insurance for Dieticians and Nutritionists

Meets NRN and Accredited Practicing Dieticians (APD) requirements
Combined Professional Indemnity and Public Liability cover
Pay by the month and policy documents emailed instantly
Cover for training clients in your own home or anywhere in Australia
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox

Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:
On this page:
What does nutrition insurance cover?
Nutrition insurance generally helps nutritionists and dieticians cover the cost of on-the-job risks, such as:
- Providing inaccurate advice or recommendations
- Malpractice claims and lawsuits
- Client property damage
- Damage to business equipment
- Personal injuries that leave you unable to work
Professional Indemnity and Public & Products Liability are mandatory to operate as a Nationally Recognised Nutritionist (NRN). Professional Indemnity insurance is also required for Accredited Practicing Dieticians (APDs).
BizCover offers affordable, dependable cover options designed to meet industry-specific risks for dieticians and nutritionists. Compare quotes and get instant policy issuance in minutes, so you can stay focused on supporting your clients.
Why do nutritionists and dieticians need insurance?
Professional Indemnity and Public & Products Liability insurance are required to work as an NRN or APD in Australia. Public[SM1] Liability may also be required to lease office or clinic space.
Nutritionists and dieticians provide expert diet, food, and nutrition advice to private clients. They may also work in the public sector, giving recommendations to local and national public health departments. Whether you’re providing meal plans, supplement advice, or long-term nutritional coaching, your guidance affects health and wellness outcomes. Providing incorrect advice, even accidentally, could lead to expensive claims.
Business insurance helps nutrition and diet professionals protect their finances from negligence claims, property damage, and other common risks. You may need insurance to:

Rent an office space.
Provide professional advice.
Pay legal costs if you face a liability claim.
Meet contract requirements.
What types of insurance do dieticians need?
We offer combined Professional Indemnity and Public & Products Liability insurance that meets industry requirements. You can build a cover package that fits your unique business needs in minutes with BizCover.

Basic cover for dieticians


Additional cover options:



Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
How much does dieticians’ insurance cost?
Business insurance for dieticians and nutritionists costs an average of $35 per month*.

How is the cost of insurance calculated?

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get cover that grows with your business
Choose from Public Liability up to $20 million and Professional Indemnity up to $10 million, including unlimited retroactive and run-off cover.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get cover that grows with your business
Choose from Public Liability up to $20 million and Professional Indemnity up to $10 million, including unlimited retroactive and run-off cover.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
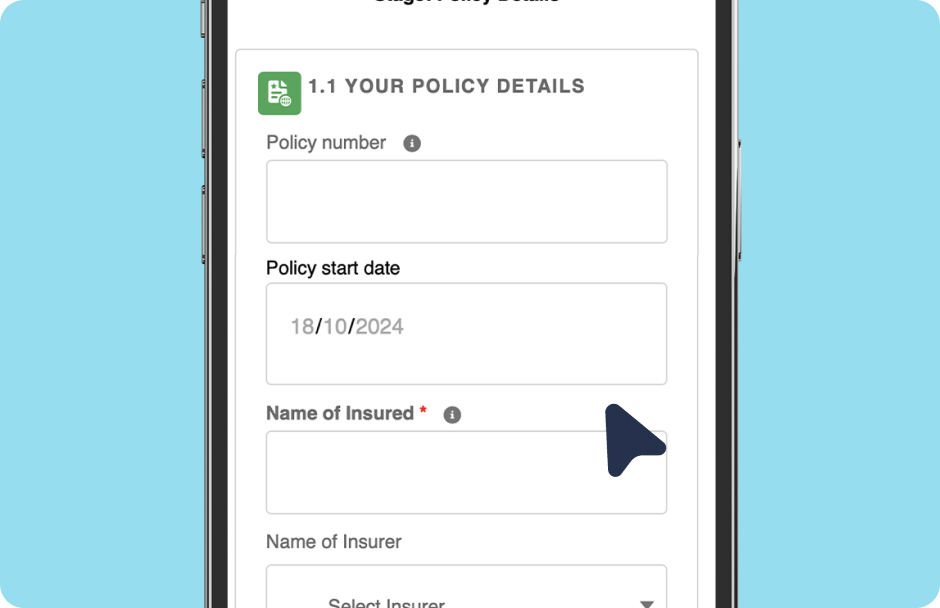
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Others Have Saved By Purchasing a Policy Through BizCover
Colette
Disability Care Worker from
NSW
Saved
$1,200
on
Public Liability and Professional Indemnity insurance
Andrea
Beautician from
VIC
Saved
$1,500
on
Business insurance Pack and,
Public Liability and Professional Indemnity insurance
Deborah
Cleaner from
VIC
Saved
$3,600
on
Public Liability insurance
Lance
Electrician from
ACT
Saved
$800
on
Public Liability insurance
Stephen
IT Professional from
VIC
Saved
$1,500
on
Information Technology Liability insurance
Linda
Restaurant owner from
NSW
Saved
$1,000
on
Business Insurance Pack and
Public Liability insurance
^ Savings made from January 2024 to April 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently Asked Questions
Is registered dietician insurance mandatory in Australia?
Yes. Dieticians Australia requires Professional Indemnity insurance to receive accreditation to become an Accredited Practising Dietician (APD).
Professional Indemnity policies offered by BizCover generally include cover for sports performance, clinical dietetics, weight control, paediatric nutrition, nutritional therapies, diabetes management, food intolerances, lifestyle wellness, gastroenterology, and much more. As with any insurance, cover is subject to the terms, conditions, and exclusions in the policy wording.
The key difference between dieticians and nutritionists is the activities they can perform.
Nutritionists can provide clients with general diet advice, feedback, and encouragement. They typically work in group education settings, such as developing community and public health programs.
Dieticians can provide the same services as nutritionists but can also prescribe menu plans and conduct medical nutrition therapy to help clients manage chronic health conditions. Dieticians must be accredited through the Dietitians Association of Australia.
Yes, nutritionist insurance can cover working with children. However, the insured nutritionist or dietician must hold appropriate qualifications and have appropriate training and/or industry experience for these activities. Cover is for nutrition and dietetic services within the insured’s scope of practice, not for medical diagnosis or treatment. Always refer to the policy wording to find out exactly what you are (and are not) covered for!
When you buy insurance with BizCover, a Certificate of Currency is emailed to you directly after payment. You can also download additional copies at any time by logging into our customer portal.
Hear from our customers
So easy to use

Shannon
Easy process and fair price
Farai
It is easy and painless process. Discount with NSNZ is a great deal!
Emma Y, Dietician
Brandon was very helpful and explained some of the variances of different policies
Andrew H, Dietician


Real-life customer reviews verified by Feefo