
Insurance for eCommerce Businesses

Public & Products Liability cover up to $20 million
Contents cover to protect your stock
Instant quotes and same-day cover
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:
On this page:
What does online retailer insurance cover?
Online retailer insurance can protect your business, stock, and equipment against costly legal claims caused by unexpected events such as theft, injury, damage, and cyberattack. Our ecommerce business insurance can cover:
- Client injury or property damage caused by the products you sell
- Replacing damaged stock or inventory
- Theft
- Cyberattacks or data breaches
- Unplanned business interruptions
BizCover understands the insurance needs of ecommerce sites and online retailers. We offer insurance options customised to ecommerce businesses, with instant cover in minutes.
Why do ecommerce businesses need insurance?
Online retailers face different risks than brick-and-mortar stores, from data breaches and stolen inventory to lost income caused by supply chain disruptions. Having appropriate online business insurance in place helps protect your business from common risks and lawsuits
| Risk scenarios |
|---|
| Customer injury or property damage caused by items you sell (including those you have imported) |
| A cyberattack exposes your customers’ personal details |
| Your business laptop is stolen |
| A delivery person slips and injures themselves in your garage |
Who needs ecommerce insurance?
Online businesses selling goods, digital protects, or services can benefit from ecommerce insurance. From side hustles to bustling online stores, we offer insurance solutions customised to ecommerce businesses.

Online Retailers
Dropshipping Businesses
Wholesalers
Virtual Marketplace Sellers
Online Food & Beverage Sellers
Online Clothing & Jewellery Stores
Online Computer & Electronics Stores
What types of insurance do online retailers need?
Finding the right e-commerce insurance for your business depends on the unique risks you may face. With BizCover, you can mix and match insurance to create an insurance portfolio that fits your unique business needs.

Basic ecommerce insurance:



Additional ecommerce insurance



Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
How much does ecommerce business insurance cost?
Business insurance for online and ecommerce retailers varies based on factors such as the size of your business and amount of cover you choose. Compare multiple quotes from selected leading Australian insurance partners to find out how much you’ll pay.
Factors influencing cost

Risks of the industry
Cover level amount
Annual Turnover
Number of Employees
Claims History
Get flexible cover to match your business needs
We offer cover levels to suit a variety of online retailers, including Public Liability up to $20 million and Cyber Liability up to $2 million.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
Get flexible cover to match your business needs
We offer cover levels to suit a variety of online retailers, including Public Liability up to $20 million and Cyber Liability up to $2 million.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
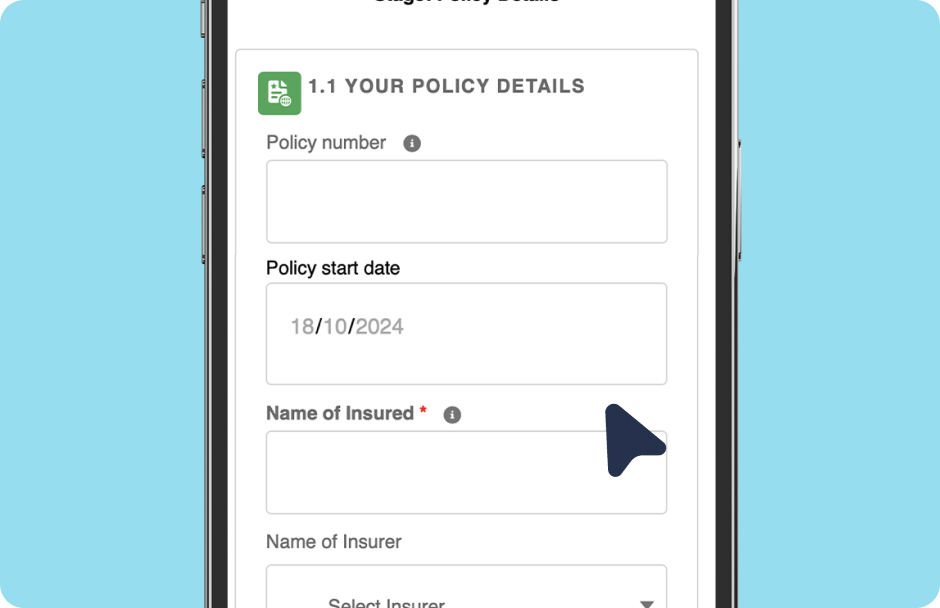
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Other eCommerce and Online Businesses Have Saved By Purchasing a Policy Through BizCover
Helen
Clothing Retailer from
TAS
Saved
$500
on
Business Insurance Pack
Rachel
Clothing Retailer from
VIC
Saved
$200
on
Business Insurance Pack
Brendan
Computer Software Retailer from
SA
Saved
$6,000
on
IT Liability Insurance

^Savings made from February to August 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
Businesses that sell from a physical premises may want to consider different types of insurance than a business that only sells online. For example, Building cover protects physical buildings that you own and operate your business from. Glass cover may also be important for protecting windows and some signage in your shop.
Business insurance might be required for some businesses that sell items on many third-party platforms. For example, Amazon requires Australian sellers to have Public Liability insurance once they hit certain sales thresholds. Always check the terms of service and/or seller agreements for third-party platforms to understand your insurance obligations (if any).
Yes, insurance generally covers dropshipping businesses. Under Australian Consumer Law, businesses are considered the manufacturer of goods that they import or sell under their own brand. If a product you have sold and dropshipped injures a customer or damages their property, you can be held liable. Public & Products Liability covers these types of claims and can help protect dropshippers.
Yes, Product Liability should be considered by ecommerce retailers. If a product you sold causes injury to a customer or damages their property, you could be held liable. Product Liability typically covers these types of claims for ecommerce retailers. It is typically part of a Public Liability policy.
Hear from our customers
The lady who assisted me on the phone was excellent.

Carlos B, Retailer
Thank you for the seamless experience!
Ryan W, Retailer
I found it quite an easy process online for obtain the quote. The staff member who rang me, Malachi, provided clear and helpful customer service.
Susan H, Retailer
Such an easy way to get insured. Love it
Andre H, Retailer


Real-life customer reviews verified by Feefo