Why shopping around matters as business insurance premiums rise
Running a small business comes with no shortage of expenses. Wages, rent, equipment, software, supplies and utilities all compete for a share of the budget.
And now, new research from BizCover suggests business insurance is adding to that pressure.
The findings paint a picture of small business owners balancing the cost of protecting their business against mounting financial pressures elsewhere. It can be a challenging balancing act for some, says BizCover General Manager Brad Miller.
“Although small business owners are incredibly resilient, these findings demonstrate that many SMEs are making difficult trade-off decisions as ongoing costs continue to rise,” says Miller.
Key takeaways
- 73% of insured small businesses saw their total insurance premiums increase in the past 12 months.
- 41% experienced an increase of 10% or more.
- 45% say premiums increased faster than revenue or increased while revenue declined.
- 23% have reduced, cancelled or not renewed some business insurance because of rising costs.
- 20% have delayed or missed an insurance payment because of cash flow pressure.
- 43% accepted their last renewal without comparing other options.
Nearly three in four businesses have seen premiums rise
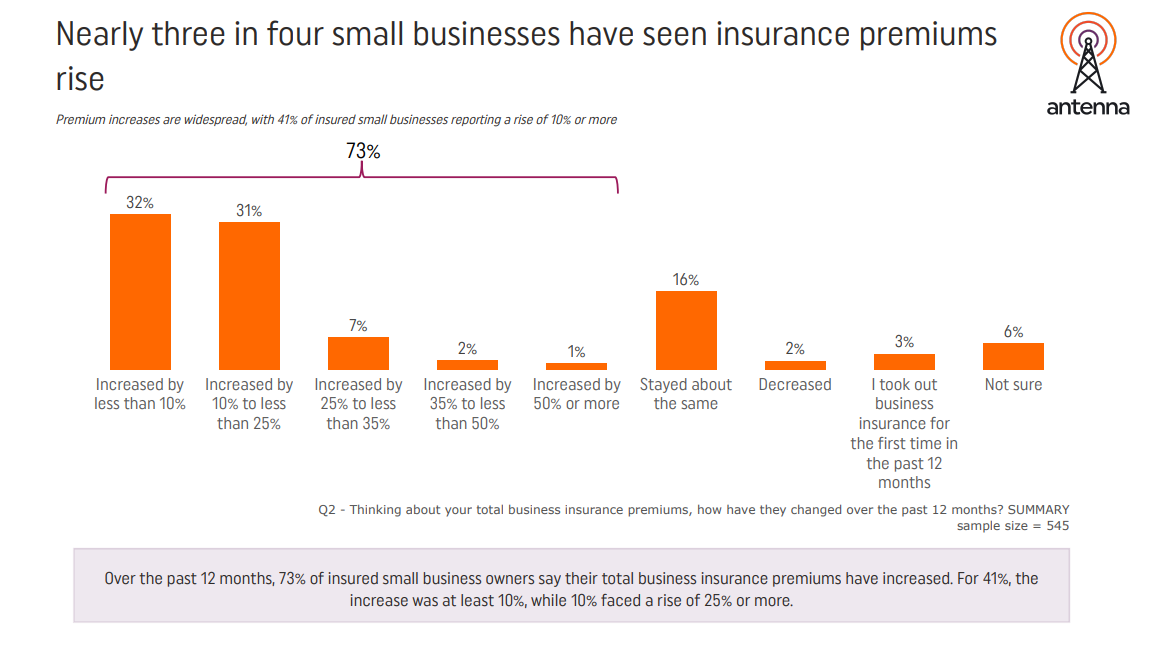
According to the data, premium increases appear to have become a common experience for insured small business owners.
Nearly three in four (73%) say their total business insurance premiums increased during the past 12 months. For 32%, premiums increased by less than 10%. Another 31% experienced increases of between 10% and less than 25%.
Only 18% said their premium stayed the same or decreased.
Insurance costs are outpacing business growth
More than one third (34%) of insured small business owners say their insurance premiums increased faster than their revenue during the past 12 months.
A further 11% experienced an even more challenging combination: their revenue decreased while their insurance premiums increased.
By comparison, just 10% say their revenue grew faster than their insurance premiums. Another 19% say premiums and revenue increased at about the same rate.
“A business might be growing, but if some of its expenses are increasing even faster, there can be less money available for investment, hiring and other operating costs,” says Miller.
How are business owners absorbing the cost?
When insured small business owners were asked what they had cut back on because of rising costs during the past 12 months, more than half (54%) said they had reduced personal or household spending. This includes everyday expenses such as coffees, takeaway, going out and groceries.
Almost one in four (23%) cut staff costs, such as reducing hours, headcount or hiring; while the same proportion said rising costs caused them to reduce, cancel or not renew some business insurance cover.
Brad Miller understands that small business owners make tough decisions every day, but says that reducing cover could end up costing a business more money in the long run.
“Small business owners are used to making difficult calls about where their money goes. But cutting back on insurance can mean taking on more of the financial risk yourself, so it’s important for owners to understand what changes to their cover could mean for their business,” he says.
Comparing insurance policies
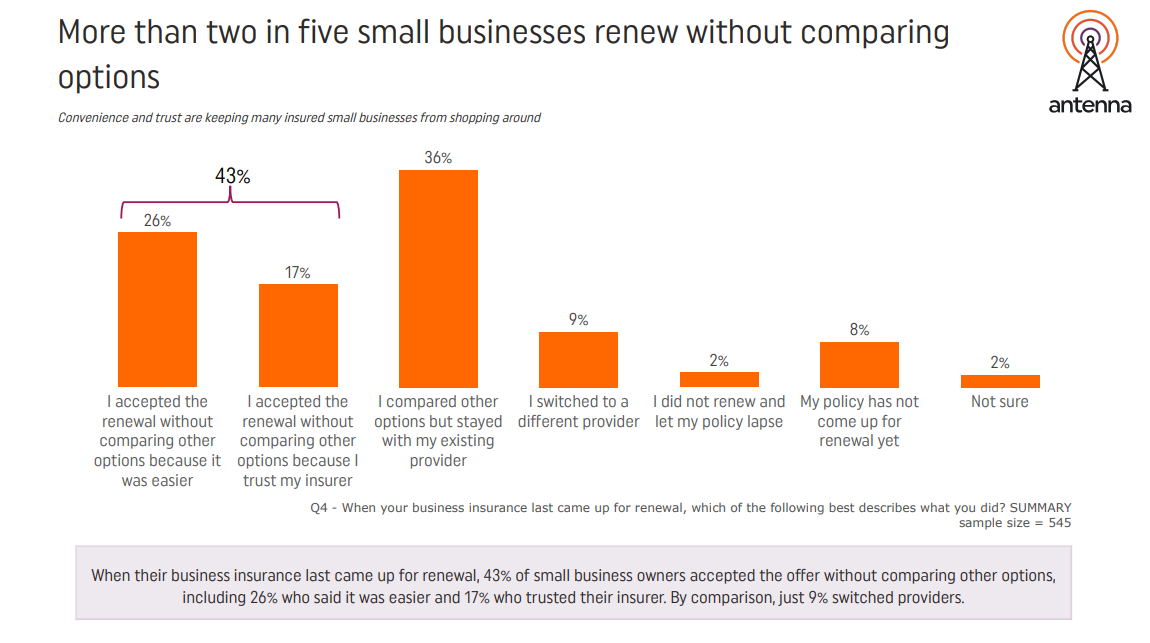
With premiums increasing, you might expect more small business owners to shop around when their insurance comes up for renewal. However, the research suggests that’s not always the case.
When their business insurance last came up for renewal, 43% accepted the offer without comparing other options. Of those, 26% said they renewed without comparing because it was easier, while 17% did so because they trusted their insurer.
Convenience and trust are understandably important to small business owners, particularly when insurance is just one of many responsibilities competing for their time.
But with almost three in four insured businesses experiencing premium increases, renewal can also provide an opportunity to review what cover a business has and explore the options available.
“Sticking with the same provider could still be the right choice for some SMEs,” says Miller. “But when costs are changing, comparing available options can help business owners make a more informed decision. It could even help them find a better price.”
Price isn’t the only consideration
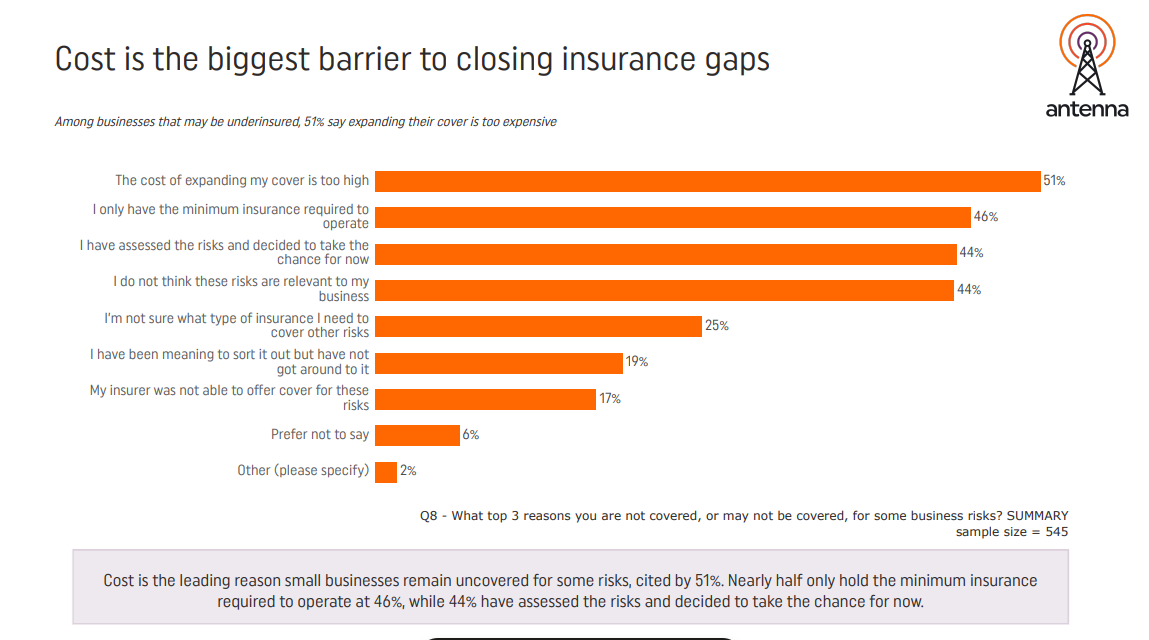
Different policies can come with different limits, exclusions, excesses and types of cover. Which means that a lower premium doesn’t necessarily mean one policy represents better value for a particular business.
Similarly, reducing cover may lower costs in the short term, but it can also change the amount of financial risk the business carries itself.
For business owners looking closely at expenses, reviewing insurance can therefore involve two separate questions: What am I paying, and what am I getting for it? Importantly, it can also help business owners better understand what level of risk they’re comfortable carrying.
The insurance balancing act for small businesses
Every business has different risks, finances and insurance considerations. The cheapest option won’t automatically be the most appropriate, just as staying with an existing provider isn’t necessarily the wrong decision.
But as costs rise, understanding existing cover and comparing the options available can give small business owners more information when deciding where insurance fits within their budget.
“Shopping around for insurance policies can help businesses understand what options are available to them and what ultimately works best for their business,” says Miller. “Whether they speak with a broker or visit a comparison website, it can help them see what is available, compare the differences and make an informed decision.”
80% of customers who used BizCover to compare insurance quotes said they saved money after switching.
“By comparing cover options, small business owners gain visibility and control over how best to manage their costs, while also helping them make sure they have adequate cover that suits their business’s needs.”
Methodology – Antenna
Antenna, an independent consumer research agency on behalf of BizCover, conducted an online AntennaPoll survey of n=545 Australian small business owners who currently have insurance. The survey was conducted between 1 and 13 of July 2026. Respondents were recruited nationally across all states and territories through an accredited online research access panel. The study was designed to capture the experiences and perspectives of this specialist audience.
Methodology – BizCover primary data
BizCover analysed pricing data for Australian customers, comparing FY24, FY25 and FY26 paid-annually prices and annualised costs for customers paying monthly across different industries and ANZSIC classifications. Year-on-year changes were calculated by comparing the relevant financial year with the previous year. The analysis reflects BizCover customer pricing data and is not intended to represent insurance pricing across the broader Australian market.
“Customer savings” data was not part of the survey. A separate BizCover customer savings survey from 2025 identified that 80% of SMEs saved when switching to BizCover.
This information is general only and does not take into account your objectives, financial situation or needs. It should not be relied upon as advice. As with any insurance, cover will be subject to the terms, conditions and exclusions contained in the policy wording or Product Disclosure Statement (available on our website). Please consider whether the advice is suitable for you before proceeding with any purchase. Target Market Determination document is also available (as applicable). © 2026 BizCover Pty Limited, all rights reserved. ABN 68 127 707 975; AFSL 501769.