

Insurance for Recruitment Consultants
Competitive pricing with our Price Promise

Professional Indemnity cover up to $10m
Instant quotes, immediate cover
Competitive pricing for individuals and agencies
Independent feedback based on verified reviews

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
Get quotes from our trusted insurance partners:


On this page:
What does recruitment insurance cover?
Recruitment insurance helps protect recruiters and employment agencies from financial losses caused by common risks, such as:
- Negligent advice or mistakes
- Third-party property damage or injury claims
- Cyberattacks and data breaches
- Wrongful acts in the management of your business
- Employment disputes within your business
BizCover offers Professional Indemnity insurance made for recruitment consultants. It may include cover for vicarious liability, automatic reinstatement, and run-off and retroactive cover (depending on the insurance partner and policy).
We understand the insurance needs of recruiters and agencies and offer cover options to help protect your business and finances in minutes.

Why do recruitment consultants need insurance?
Recruiters and staffing agencies may need insurance to help protect their business, meet contractual obligations, and cover some unplanned expenses (such as legal defence fees.
| Industry-specific risks | General risks |
|---|---|
| Placing a candidate with inadequate experience into a role they are not suited to | A jobseeker trips over loose carpet in your office and is injured |
| A claim is made against you for the actions of an on-hired employee | A data breach exposes client and jobseeker details |
| You fail to perform a necessary background check on a candidate | A former employee makes an unfair dismissal claim against your agency |
Who needs recruitment insurance?
Recruitment insurance is considered by many types of businesses, including consultants, career advisors, labour hire services, and employment agencies. Whether you’re a freelance recruiter or a growing agency, we offer tailored insurance options to help protect your business.

Recruitment Agencies and Consultancies
Labour Hire Services
Employment Agencies
Career Advisors
Executive Search Services
Model Agencies
Temp Agencies
Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
What types of insurance do recruiters need?
Recruiters may consider a range of insurance options to help protect their finances, business, and clients. We offer insurance options designed for recruitment businesses.

Basic recruiter insurance


Additional recruiter insurance




How much does recruitment insurance cost?
Business insurance for recruitment consultants costs an average of $121 per month*.
Factors influencing cost

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Flexible cover that grows with your business
Choose insurance limits to fit your business needs, from sole traders to growing recruitment agencies. Professional Indemnity up to $10 million, Public Liability up to $20 million, Cyber Liability up to $2 million, and Management Liability up to $5 million.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Factors influencing cost
Risk of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*BizCover’s Marketing Pricing Expectations Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Flexible cover that grows with your business
Choose insurance limits to fit your business needs, from sole traders to growing recruitment agencies. Professional Indemnity up to $10 million, Public Liability up to $20 million, Cyber Liability up to $2 million, and Management Liability up to $5 million.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to over yourself, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How It Works – Buying Online
5 easy steps to get instant cover online today

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online
5 Steps to get your biz insured:

- Enter Occupation
Search & select your occupation


- Choose Cover(s)
Select the cover you need

- Business Details
Tell us about your business

- Compare Quotes
Compare prices & select quotes
- Get Cover Today
Instant policy docs to your inbox.
How To Make a Claim Online
We’ll assist you through the claims process & manage the claim directly with the insurer.
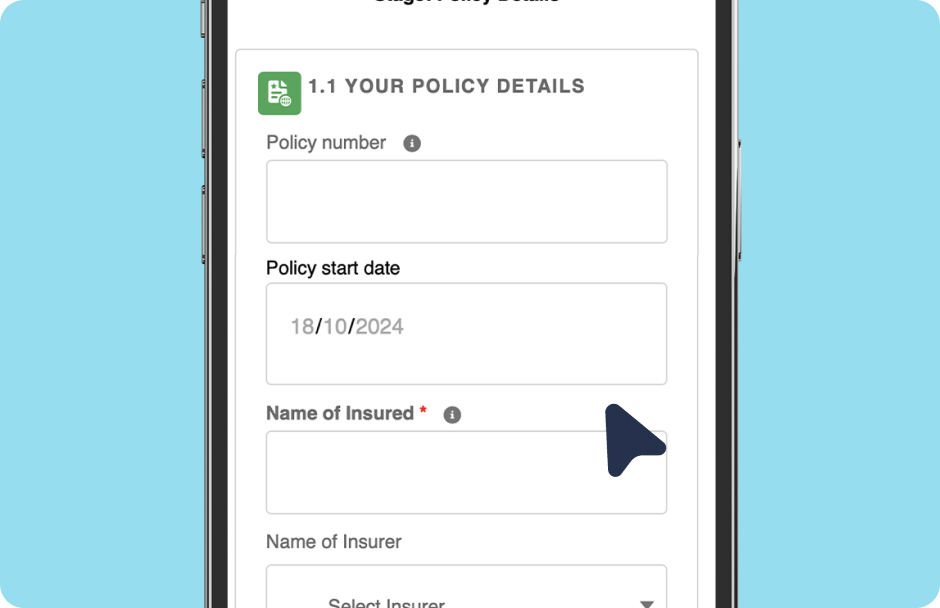
Let us know Fill out our
claims form and provide info
to support the claim
Receive extra support We
will assist you with your claim
Claim results We will notify
you of the claim outcome.
3 steps to get your biz insured:
- Let us know
Fill out our claims form and provide info to support the claim.
- Receive Extra Support
We’ll assist you with your claim.
- Claims Results
We’ll notify you of the claim outcome.
Award-Winning Tech & People
We’re not ones to blow our own trumpet, but we are pretty proud of our innovative insurance platform, outstanding team, and stellar workplace.
See How Much Other Recruitment Consultants Have Saved By Purchasing a Policy Through BizCover
Sumit
Recruitment Consultant from
WA
Saved
$200
on
Professional Indemnity and Public Liability insurance
Mandy
Recruitment Consultant from
NSW
Saved
$1,300
on
Professional Indemnity, Cyber Liability and Public Liability insurance

^Savings made from February to August 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
While insurance is generally not required by law for recruitment consultants, there are times when it may be necessary. For example, Professional Indemnity and/or Public Liability insurance may be required in a work contract. Public Liability insurance may also be mandatory to lease office space for your business.
Yes, independent recruitment consultants may want to consider Professional Indemnity insurance to help them protect their business and finances. Professional Indemnity claims can be expensive. A Professional Indemnity policy helps independent recruiters cover legal costs, compensation payments, and settlements and judgements related to their services, advice, and recommendations.
Yes, Professional Indemnity insurance can cover mistakes made by your recruitment staff. When you purchase a policy, you can choose how many people will be covered by the policy in order to cover your staff.
Professional Indemnity cover for labour hire placements is available from some insurance partners. Cover may be limited to specific occupations, and subject to exclusions and sub-limits.
Vicarious liability is when a person or organisation is held liable for the actions of another person or organisation, even though they were not directly responsible for the damage or injury that was caused. For example, a business owner may be held vicariously liable for mistakes made by an employee or contractor. Some insurance policies, such as Professional Indemnity, will cover vicarious liability.
The main difference between employment agencies and recruitment agencies is who they work for. Employment agencies help jobseekers find jobs; recruitment agencies help employers find candidates for their open positions.
A retroactive date is the earliest date from which a policy will cover you. Retroactive cover provides protection for claims that arise from work completed before the start of the current policy period. [SM11.1]This typically applies to Professional Indemnity policies, where it may be months or years after work has been completed before a claim is made against you.
Professional Indemnity and Public Liability are common types of insurance that many recruitment consultants consider for their businesses. Each provides different, protection:
Professional Indemnity insurance offers protection for businesses that provide specialist services or professional advice. It is designed to respond to claims against your business for losses as a result of actual or alleged negligent acts or omissions in the provision of your professional service or advice. PI Insurance will also assist with the legal costs associated with responding to or managing claims which are covered by the policy.
Public Liability insurance is designed to provide protection for you and your business in the event a customer, supplier or a member of the public brings a claim against you due to their being injured or sustaining property damage as a result of your negligent business activities.
Professional Indemnity generally protects you and your recruitment agency, not individual candidates placed with clients. Always check your policy wording to understand exactly what you are and are not protected for.
Hear from our customers
Consultant was professional and knowledgeable of products and services.

Ondrea T, Recruiter
Super helpful and easy to arrange over the phone. Small wait time.
Adrian P, Recruiter
Ease of sign-up, confidence in product.
Christina C, Recruiter
Excellent customer service.
Dave C, Recruiter


Real-life customer reviews verified by Feefo